Best Mutual Funds for Beginners India 2026
October 21, 2026


TABLE OF CONTENTS
Get AI Summary
Best mutual funds for beginners in India are low-cost Nifty 50 index funds and balanced advantage funds that automatically adjust equity exposure. These categories keep costs low, diversification high, and day-to-day decisions minimal so first-time investors can focus on staying invested.
The Indian mutual fund industry managed assets of Rs 82.64 lakh crore as of 30 September 2026, according to the Association of Mutual Funds in India (AMFI). Equity-oriented schemes recorded net inflows of Rs 38,307 crore in September, marking the 67th consecutive month of positive equity flows. SIP contributions hit a fresh record of Rs 32,490 crore the same month, with more than 10 crore contributing SIP accounts. For someone starting today, the practical first step is a monthly SIP in a fund that tracks a broad index or that mixes equity and debt under clear rules. You can compare the cost and tracking differences in the mutual funds vs index funds article before choosing.
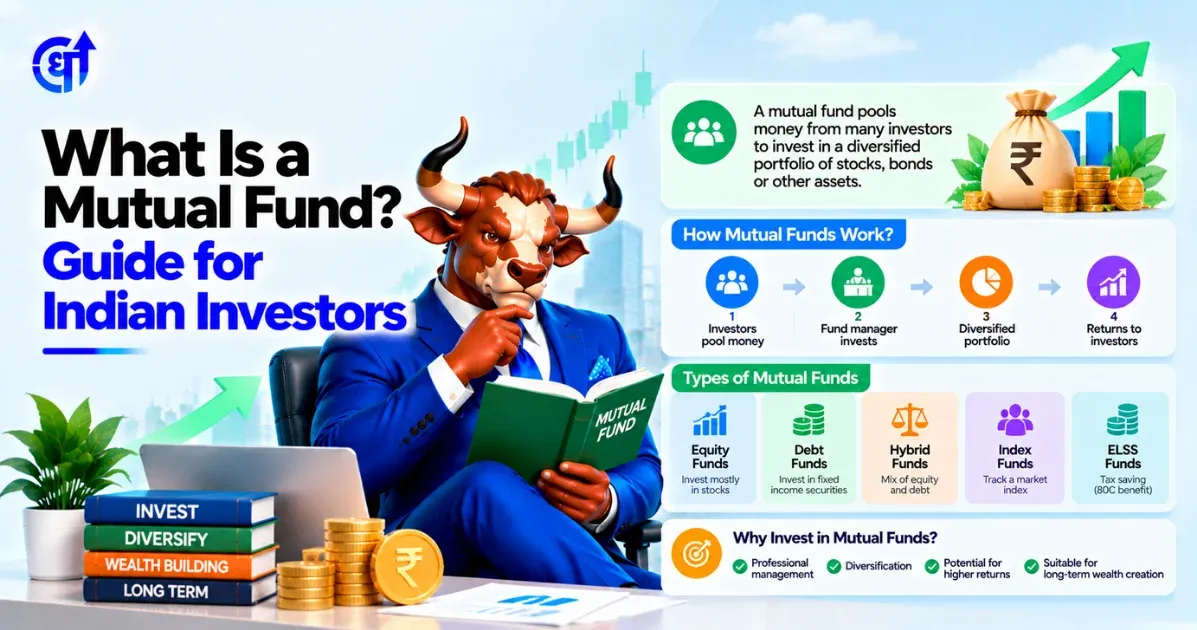
A mutual fund collects money from many investors and invests it according to a published mandate. One fund can hold dozens of stocks. If one company reports weak results, the impact on the overall portfolio stays limited. Buying individual shares requires reading quarterly results, understanding debt levels, and tracking sector cycles. Most new investors do not have the time or the tools for that work. Mutual funds remove that burden.
AMFI data for September 2026 shows that retail participation through SIPs continued even while total industry AUM fell 5.1 percent month-on-month. Equity AUM declined because of mark-to-market losses, yet fresh equity inflows rose more than 30 percent from August. Investors who kept their SIPs running bought additional units at lower prices. That automatic averaging is the main reason systematic plans have become the default route for long-term goals among retail investors.
A frequent error is to stop the SIP after two or three months of negative returns. Markets can stay range-bound or fall for several quarters. The investor who paused in September 2026 missed the chance to accumulate units while valuations were lower. History of SIP accounts shows that the majority of long-term wealth is created by continuing the same debit every month rather than trying to time entries.
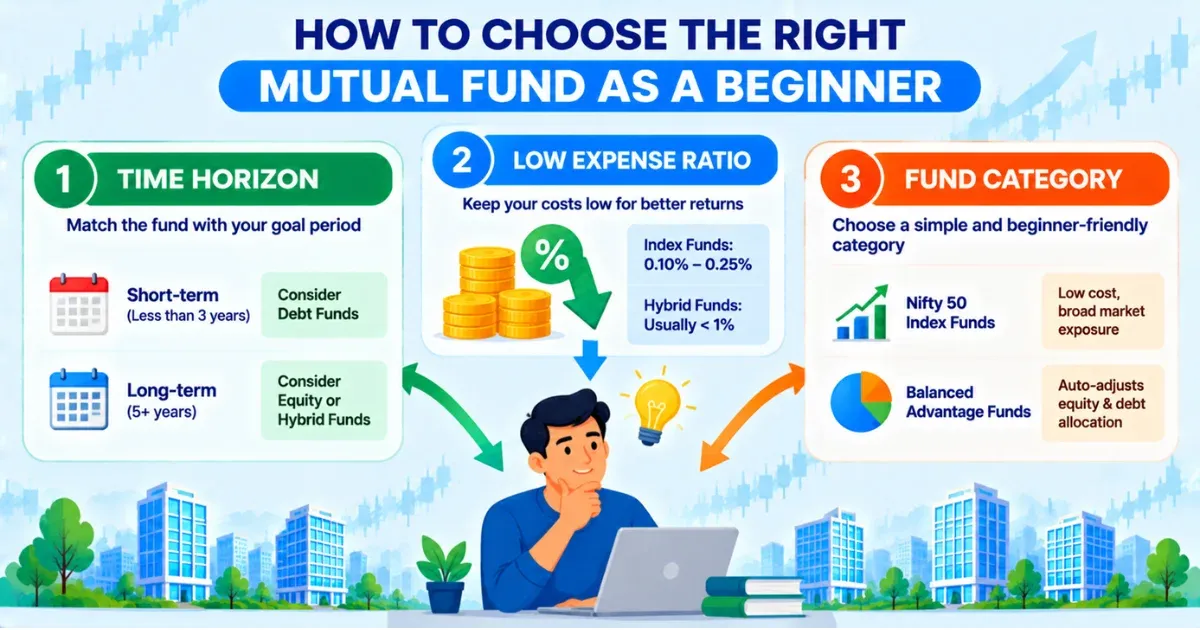
Use three simple filters before you register any SIP.
Time horizon comes first. Equity-oriented funds need at least five years. Shorter goals are better served by debt or hybrid schemes with higher debt allocation. Expense ratio is the second filter. Index funds charge as little as 0.10 to 0.25 percent in direct plans. Active hybrid funds in direct plans usually stay under 1 percent. The third filter is the category mandate. SEBI defines what each category can and cannot do. A Nifty 50 index fund must replicate the index. A balanced advantage fund can shift the equity weight based on its valuation model. Read the latest factsheet for the exact equity percentage and top ten holdings.
Direct plans are available on most platforms. They remove the distributor commission that regular plans carry. The difference of 0.5 to 1 percentage point compounds over a decade and leaves more money in the investor’s account. Always confirm you are selecting the direct plan before completing the KYC and bank mandate.
These funds buy the same 50 stocks that make up the Nifty 50 in the same weights. No fund manager selects or rejects companies. The expense ratio is the lowest available in equity products. UTI Nifty 50 Index Fund reported an AUM of Rs 28,064 crore as of 30 September 2026 and a direct-plan total expense ratio of 0.25 percent (Source: UTI Mutual Fund and AMFI). The largest holdings include HDFC Bank at about 10 percent of the portfolio and Reliance Industries near 7.5 percent. Infosys and other large technology and financial names also appear in the top ten.
One-year returns for most Nifty 50 index funds were negative as of mid-October 2026 because the underlying index itself had declined. Three-year and five-year returns remained positive in the mid-single digits. The tracking error stays very low, usually under 0.05 percent on a one-year rolling basis for the larger funds. For a beginner, the product is transparent: if the Nifty 50 rises 10 percent, the fund rises roughly 10 percent minus the small expense.
Balanced advantage funds, also called dynamic asset allocation funds, use a quantitative model to raise or lower equity exposure. When equity valuations look high, the model reduces equity and increases debt or cash. When valuations look reasonable, equity weight rises. ICICI Prudential Balanced Advantage Fund managed Rs 71,913 crore as of 30 September 2026 (Source: AMFI). Its direct-plan expense ratio is around 0.71 percent. Three-year returns stood near 10 percent as of October 2026.
The automatic shift reduces the need for the investor to decide when to move money between equity and debt. That feature is useful for first-time investors who want equity participation but do not want to watch daily market moves. Exit loads usually apply only if more than a certain percentage of units are redeemed within one year. Check the scheme document for the exact limit.
Flexi cap funds can invest across large-cap, mid-cap, and small-cap stocks without fixed percentage limits. Parag Parikh Flexi Cap Fund held Rs 1,45,070 crore as of 30 September 2026, making it the largest equity scheme in the industry (Source: AMFI). The fund also maintains a portion in international equities and cash. Direct-plan expense ratio is typically under 0.70 percent. Three-year returns were around 12.5 percent while one-year returns were negative.
Beginners who already hold a Nifty 50 index fund can later add a flexi cap fund for broader exposure. The active decisions of the fund manager introduce an additional layer of variability. Results depend on stock selection as well as market direction. Many advisors suggest waiting until the investor has stayed through at least one full market cycle before adding actively managed flexi cap exposure.
Research Stocks Smarter with Dhanarthi AI Screener
Analyze 5,000+ NSE & BSE stocks with 150+ custom filters, real-time volume breakout scans, and transparent fundamental data.
Use Dhanarthi Screener
| Fund Name | Category | AUM (Rs Crore, 30 Sep 2026) | Direct Expense Ratio | 3-Year Return (approx.) |
|---|---|---|---|---|
| UTI Nifty 50 Index Fund | Index | 28,064 | 0.25% | 6.3% |
| ICICI Prudential Balanced Advantage Fund | Balanced Advantage | 71,913 | 0.71% | 10.3% |
| Parag Parikh Flexi Cap Fund | Flexi Cap | 1,45,070 | 0.69% | 12.5% |
| HDFC Flexi Cap Fund | Flexi Cap | 1,08,547 | 0.77% | 14.4% |
Data sourced from AMFI and individual fund factsheets. Last updated: October 2026.
The table illustrates that size and recent returns do not always move together. Parag Parikh Flexi Cap Fund is the largest equity fund yet posted a negative one-year return while some smaller schemes in the same category showed higher numbers. For beginners the relevant metrics are expense ratio, consistency across market cycles, and clarity of the mandate. Short-term rankings change every quarter and should not drive the first purchase decision.
A simple two-fund portfolio works for most first-time investors.
For a Rs 5,000 monthly SIP:
For a Rs 10,000 monthly SIP:
After 24 to 36 months of consistent investing, a portion of the new SIP can be directed to a flexi cap fund. The existing units stay in place. This gradual addition keeps the core allocation stable. AMFI schemes accept SIPs from Rs 100 or Rs 500 depending on the fund house. Starting at a comfortable amount and increasing it by 10 percent each year (step-up SIP) is more sustainable than trying to invest a large sum at once.
Investors who later want pure equity growth can review the structure of monthly plans in the best mutual funds investment SIP plans article. Those who prefer listed passive products can also examine exchange-traded funds. The guide on exchange traded funds ETF explains liquidity, expense, and tracking differences between ETFs and index mutual funds.
Selecting a fund solely because it topped the one-year return list is the most frequent error. Small-cap funds attracted Rs 9,039 crore in net inflows in September 2026, the highest among equity categories. Those same funds also experienced larger drawdowns when the broader market declined. Beginners who bought only the recent winner often saw bigger losses than investors who stayed with large-cap or hybrid schemes.
Choosing the regular plan instead of the direct plan is another costly habit. The extra expense compounds. Over ten years the difference can equal several months of SIP contributions. Most online platforms now default to or clearly label direct plans. Confirm the plan type before the first debit.
Stopping the SIP during a correction is the third common mistake. September 2026 saw industry AUM fall 5.1 percent, yet new SIP registrations continued at a high pace. Investors who paused missed lower unit prices. Restarting later at higher prices reduces the averaging benefit.
Ignoring exit loads and lock-in periods creates unexpected friction. Most equity and hybrid funds charge an exit load on redemptions within 365 days. ELSS tax-saving funds lock units for three years. Read the scheme information document before the first investment.
Equity-oriented mutual funds held for more than 12 months attract long-term capital gains tax of 12.5 percent on gains exceeding Rs 1.25 lakh in a financial year. Gains within 12 months are taxed at 20 percent as short-term capital gains. Debt-oriented funds are taxed according to the investor’s income-tax slab. Balanced advantage funds that keep equity exposure above 65 percent generally receive equity tax treatment. The exact equity percentage appears in the monthly factsheet. Tax rates can be revised in the Union Budget, so verify the current rates on the income-tax website or with a qualified advisor before redeeming units.
Dividends, if any, are added to the investor’s income and taxed at slab rates. Most growth options reinvest the gains, so the investor pays tax only at the time of redemption. This structure suits long-term goals better than regular income options for beginners.
The investor completes KYC once, links a bank account, and sets the SIP date and amount. On the chosen date each month the amount is debited and units are allotted at that day’s net asset value. No further action is required unless the investor wants to change the amount, pause, or stop the plan. In September 2026 the industry registered approximately 63 lakh new SIP accounts. Contributing SIP accounts crossed 10 crore. The average ticket size has risen over the years, yet a large number of accounts still run between Rs 500 and Rs 2,000 per month.
The low minimum makes mutual funds accessible. A person who can set aside Rs 1,000 each month can begin immediately. Over 15 to 20 years the combination of regular contributions and market growth produces a meaningful corpus for goals such as children’s education or retirement. The key is to choose the date that matches the salary credit and to avoid changing the date frequently.
AMFI publishes the monthly industry snapshot that includes total AUM, category-wise inflows, SIP numbers, and folio counts. SEBI defines the category boundaries and the disclosure standards every fund must meet. Both organisations make the data public so any investor can verify a fund house’s claims. Before investing, open the latest factsheet or the AMFI monthly note and confirm the AUM, expense ratio, and portfolio holdings. Marketing material can highlight recent returns; the official documents show the complete picture.
SEBI also requires every scheme to display a riskometer that rates the product from low to very high risk. Beginners should match the riskometer with their own ability to tolerate temporary declines. A very high risk rating on an equity fund is normal; it simply means the value can fall sharply in the short term.
Review the portfolio once a year, preferably at the same time each year. Check whether the original goal and time horizon remain the same. If income has risen, increase the SIP amount. If a major life event changes the goal, adjust the allocation. Do not review the portfolio every week. Short-term movements create noise that often leads to unnecessary switches.
Keep emergency savings in a liquid or overnight fund or in a savings account. Equity mutual funds are not suitable for money that may be needed within the next three years. Separate the emergency corpus from the long-term SIP. This separation prevents the investor from redeeming equity units during a temporary cash need.

Confused about chart patterns & stock analysis?
Use
Dhanarthi Stock Guru
to chat, analyze price patterns, and ask questions directly.
Beginners do not need a complex portfolio on day one. A Nifty 50 index fund combined with a balanced advantage fund covers low cost, broad diversification, and automatic risk management. Add a flexi cap fund only after the investor has remained invested through at least one complete market cycle. Review the allocation once a year and step up the SIP amount when income allows. The September 2026 AMFI numbers show that SIP inflows continued to rise even while overall industry AUM declined. That pattern confirms disciplined monthly investing remains the most practical starting path for new retail investors in India.
This article is for educational purposes only. It does not constitute investment advice. Please consult a SEBI-registered financial advisor before making investment decisions.
1. What are the best mutual funds for beginners in India?
Nifty 50 index funds and balanced advantage funds are the most suitable starting options. UTI Nifty 50 Index Fund and ICICI Prudential Balanced Advantage Fund are commonly used because of their low costs and clear investment rules. Begin with a monthly SIP rather than a large one-time amount.
2. How much should a beginner invest in mutual funds?
Most schemes accept SIPs from Rs 500 per month. A practical starting range is Rs 2,000 to Rs 5,000 split between one index fund and one hybrid fund. Raise the amount by 10 percent every year as salary increases.
3. Are index funds better than active funds for beginners?
Index funds charge lower fees and simply follow the market. Over long periods many active large-cap funds do not beat the Nifty 50 after expenses. Beginners benefit from the lower cost and simpler structure of index funds.
4. What is the minimum time horizon for equity mutual funds?
Five years is the practical minimum for equity-oriented funds. Shorter periods leave the investor exposed to market declines that can produce negative returns. Balanced advantage funds can be considered for horizons of three to five years.
5. Do beginners pay tax on mutual fund gains?
Equity mutual fund gains above Rs 1.25 lakh held longer than 12 months are taxed at 12.5 percent. Gains within 12 months are taxed at 20 percent. Debt funds are taxed at the investor’s income slab rate. Confirm the latest rates before redeeming any units.
Share Market
IPO
Artificial Intelligence
Semi Conductor